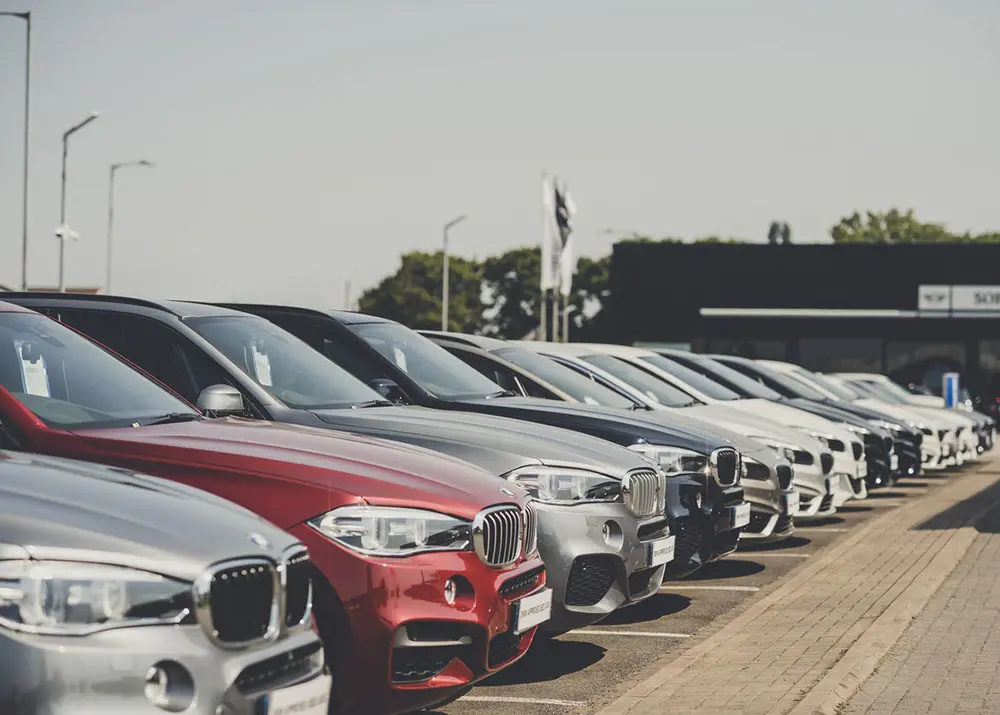
The new car market has entered the final quarter of 2026 with firm underlying momentum, as the latest data from Autotrader reveals consumer engagement has held firm following the busy September plate change period, supported by intensifying competition, greater consumer choice and attractive offers across a widening range of brands and models.
Traffic to Autotrader’s new car platform in October is level year-on-year (YoY), indicating that consumer car buying demand has remained stable in line with seasonal expectations after one of the busiest periods in the new car calendar. It follows a strong September plate change, which saw new car registrations rise 12% YoY[1].
The data also reveals that the volume of new cars advertised on Autotrader in October is 13% higher than a year ago, giving greater choice for car buyers as competition across the market intensifies. The continued growth of new entrant brands is prompting established manufacturers to respond with more competitive pricing and attractive offers; whilst softening slightly on September’s levels, average advertised discounts remain substantial at 10.2% across all fuel types and 10.1% for electric cars[2]. This combination of greater choice and improved affordability are helping to sustain demand as the market enters the final quarter of 2026.
Sustained demand into Q4 reinforces upgraded full year outlook
This ongoing performance reinforces Autotrader’s recently upgraded full year market forecast. The platform expects 2.21 million new car registrations in 2026 – representing an annual growth of 9.5% and placing the market ahead of expectations at the start of the year.
Autotrader calls for ZEV mandate flexibility amid mixed Government messaging and geopolitical volatility
The market’s current strength highlights the importance of Government policy stability and clear communication as the transition to electric progresses. With the latest ZEV Mandate review closing today, Autotrader is reinforcing its support for maintaining the 2030 and 2035 phase-out dates to provide regulatory certainty and preserve the UK’s long term decarbonisation ambitions.
However, it warns that protecting market health requires a pragmatic approach to the intervening trajectory. With current levels of electric demand so dependent on fuel prices, and against the current backdrop of geopolitical uncertainty, it remains unclear but unlikely that steep jumps in annual targets will be achievable - made even more difficult by the introduction of electric Vehicle Excise Duty (eVED) in 2028. Autotrader believes greater flexibility in the near-term targets would help manufacturers manage these industrial and commercial pressures without weakening the UK’s long-term environmental ambitions.
Electric demand reflects widening consumer choice
The broadening competitive landscape is particularly evident in the electric market. Driven by expanding model choice across premium, established volume, and new entrant brands, October marked the first time electric cars accounted for more than a third (33.8%) of all new car enquiries on Autotrader.
BMW continues to lead new electric brand interest on the platform, capturing nearly a tenth of all electric enquiries (9.4%), while Chinese manufacturer BYD holds second spot (6.2%), followed by Hyundai (5.8%) and Kia (5.6%). Model-level enquiry data highlights how consumer appetite is expanding across a diverse mix of vehicle types: the premium BMW iX3 leads new electric enquiries in October so far (4.7%), closely followed by the compact, retro-inspired Renault 5 E-Tech (4.4%) and Cupra’s Raval (3.8%).
A similar dynamic is shaping overall market demand across all fuel types. While established manufacturers continue to command the largest overall share – led by BMW (9.8%), Land Rover (7.9%), and Volkswagen (6.7%) – the growing enquiry shares achieved by challenger brands such as Jaecoo (5.2%) and Chery (4%), demonstrates how widening brand choice is reshaping consumer consideration.